✦ Key Takeaways · 6 min read
Weak audit evidence silently erodes the credibility of every conclusion your report makes.
→ Poor evidence quality exposes your entire audit to challenge.
→ Relevance and reliability together determine whether evidence actually holds up.
→ Modern tools can close the gaps traditional collection methods leave open.
In this article:
Why Weak Audit Evidence Quietly Undermines Your Report
What Determines the Quality of Audit Evidence?
How to Fix the Most Common Evidence Collection Mistakes
Modern Tools That Strengthen Audit Evidence Quality
Turn Better Evidence Into a More Credible Audit Report
Conclusion
Key takeaway: Fix your evidence first, and every other part of your audit report fixes itself.
Why Weak Audit Evidence Quietly Undermines Your Report

Why Weak Audit Evidence Quietly Undermines Your Report
Thin findings don’t announce themselves. They sit inside your report looking credible. Meanwhile, decision-makers quietly discount your conclusions because the proof doesn’t quite match the claim.
Say your team flags a procurement risk and backs it up with a vendor invoice count. That number shows volume, not control failure. Audit evidence sufficiency and appropriateness are two different tests, and most reports pass one while quietly failing the other.
The real damage stays invisible until it’s too late. A filed report that changes nothing isn’t a communication problem. It’s an audit evidence collection problem that started long before anyone wrote the executive summary. So what actually makes a piece of supporting material strong enough to hold up?
What Determines the Quality of Audit Evidence?
Good evidence still falls short if it doesn’t connect to the specific claim you’re trying to prove. Assertion alignment is the discipline that separates high-quality audit evidence from evidence that merely looks complete.
Think of it this way: a signed inventory count sheet proves existence. It tells you nothing about whether that inventory is valued correctly.
Most auditors collect evidence by habit, grabbing what’s available and familiar. They rarely stop to ask, “What exact assertion does this document support?” That gap is where audit evidence collection methods either earn their keep or quietly fail the report.
Sufficiency vs. Appropriateness: The Core Distinction
Sufficiency is about quantity: do you have enough evidence to support your conclusion? Appropriateness is about quality: is each piece relevant to the assertion, and is its source reliable? Both tests must pass on their own, because a large volume of weak evidence is still weak evidence.
Say your team pulls 200 invoices to test completeness of revenue. That’s enough in volume, but those invoices only confirm that transactions were recorded. If they don’t show whether all transactions were captured, you’ve missed the assertion entirely.
Audit evidence sufficiency and appropriateness work together, but they’re never interchangeable.
External vs. Internal Sources: Reliability Hierarchy
Not all evidence carries the same weight. A bank confirmation sent directly to the auditor comes from an independent external source. That ranks higher in audit evidence reliability than an internal schedule that management created and controls.
This hierarchy matters because decision-makers sense it, even when they can’t name it. A report built on direct confirmations and third-party data earns a higher level of trust. One built on management representations alone does not. Choosing the right source for each assertion is a deliberate act, not a default.
The habits that determine which sources you reach for first are exactly where most evidence quality problems begin.
Improve Audit Evidence Quality in 5 Steps
1. Define the Requirement Before Collecting Evidence
Identify the policy, approved layout, price list, or other criterion behind each check. Specify the version and date that apply to the location.
Write the question so two auditors can evaluate the same condition consistently. “Does the display match the approved campaign assortment?” gives the auditor a clearer task than “Does the display look correct?”
2. Capture the Observation With Context
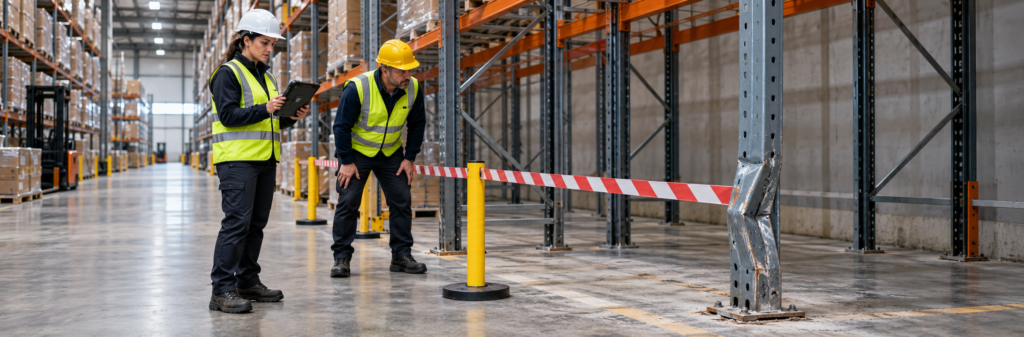
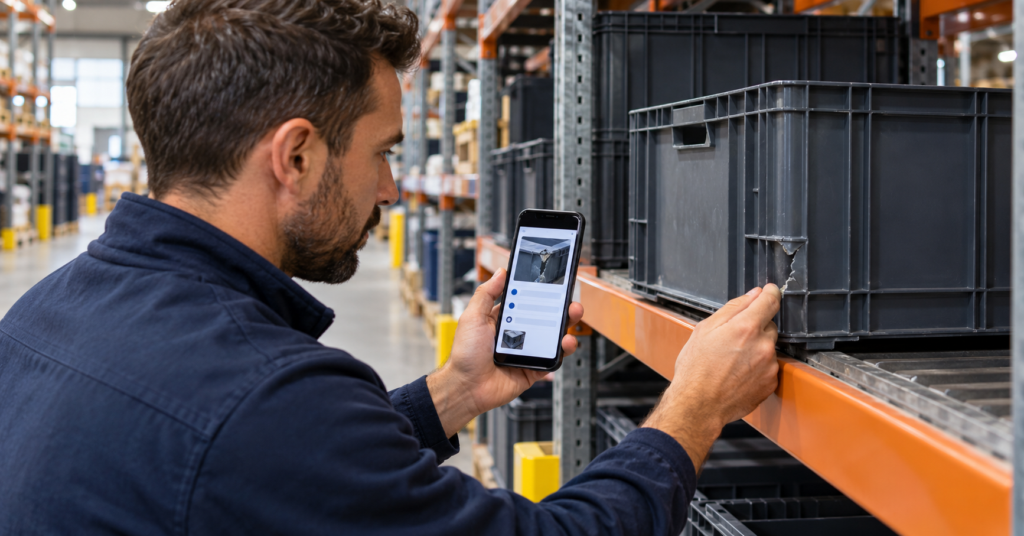
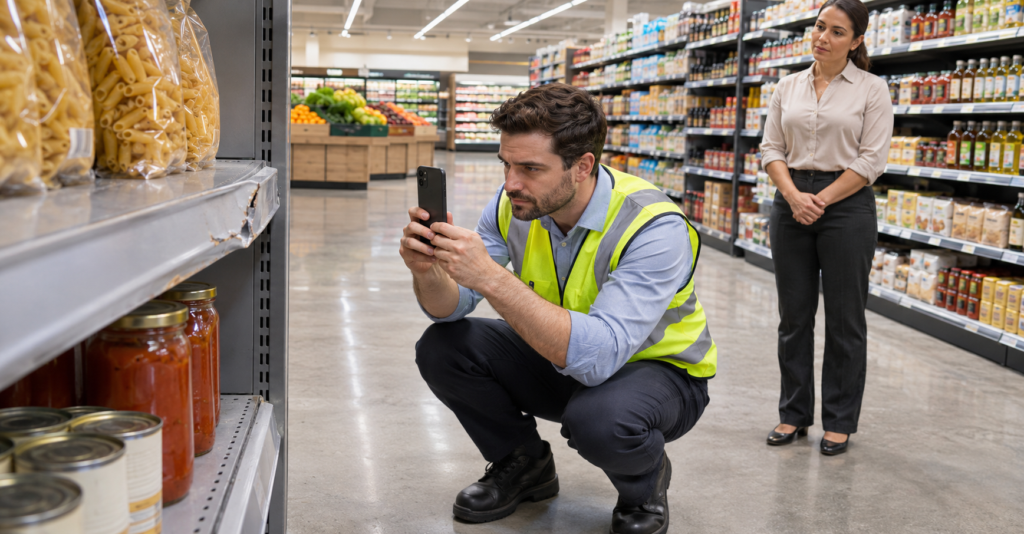
Record the store, asset or SKU, check, capture time, and observed condition. Take photos that show both the issue and enough surrounding detail to identify its location.
Use required fields and consistent capture instructions to reduce missing context. Apply inspection data validation before submission so incomplete records can be corrected while the auditor is still on-site.
3. Evaluate the Source and Resolve Contradictions
Check how the evidence was created and whether the relevant records are complete. When an audited team supplies a report, review its scope, date range, and selection criteria before relying on it.
Investigate conflicting information. If the inventory system shows stock but the shelf is empty, check the backroom and physical count before concluding that the store has no inventory. Record what remains uncertain.
4. Preserve Original Records
Keep original files alongside any annotated or cropped copies. Restrict access appropriately and retain a record of changes and reviews.
For workflows requiring file integrity checks, hashes can help identify whether a file has changed since a reference hash was recorded. A matching hash supports file integrity, while the original observation and its context still require evaluation. NIST discusses these controls in its digital evidence preservation
5. Review the Finding Against the Evidence
Before issuing the report, ask another reviewer to trace the finding back to the requirement, observation, and supporting records.
Check whether the wording stays within the evidence collected. If the auditor checked three displays, describe those three displays and the results. Identify any sampling or access limitations that affect the conclusion.
Modern Tools That Strengthen Audit Evidence Quality
Fixing evidence habits is only half the job. The right tools make assertion alignment repeatable, not accidental.
Assertion mapping software: These tools link each evidence item directly to the specific claim it must support. That means gaps show up before fieldwork ends, not after.
Automated sampling engines: They select samples based on risk criteria you define, removing the unconscious bias that skews manual selection toward familiar records.
Continuous monitoring platforms: Instead of a point-in-time snapshot, these tools flag anomalies as they happen, strengthening reliability across the full review period.
AI-assisted exception detection: Say your team reviews ten thousand transactions. AI surfaces the outliers that matter, so auditors focus their judgment where it counts most.
Audit evidence repositories: Centralized storage with version control keeps records intact and traceable. That continuity is critical for audit data quality practices that hold up under scrutiny.
Data Analytics and Automated Testing Techniques
Data analytics lets auditors test entire populations instead of samples. That closes the coverage gap that partial testing always leaves open. A full-population test of vendor payments, for example, catches duplicate invoices that a standard sample would almost certainly miss.
Automated testing also enforces consistency. Every transaction gets evaluated against the same criteria. Sufficiency and appropriateness no longer depend on who ran the test or how tired they were that afternoon.
Authenticating and Preserving Digital Evidence
Collecting digital evidence is easy; proving it hasn’t changed since collection is the hard part. Hash verification, a standard technique in digital forensics, generates a unique fingerprint for each file. Any alteration becomes immediately detectable.
Preservation matters just as much as collection. High-quality findings lose their value fast if the chain of custody breaks. A skeptical reviewer can dismiss the whole file on procedural grounds alone.
Well-collected, properly verified records mapped to a specific assertion give every conclusion in your report a foundation that’s genuinely hard to challenge. That’s what separates a defensible report from one that unravels under review.
Turn Better Evidence Into a More Credible Audit Report
Closing those evidence gaps is only half the job. The other half is turning what you found into report language that moves people to act. Every conclusion needs a clear path back to the proof, or the work behind it goes to waste.
Say your team used automated sampling to flag a pricing discrepancy at a retail location. Don’t write “pricing controls appear inconsistent.” Write “automated sampling identified three locations where shelf prices differed from the approved price list on the same date.” The second version names the assertion, names the evidence, and leaves no room for doubt. That discipline separates reports that change behavior from reports that get filed and forgotten.
FieldPie’s audit module captures timestamped field data and photo evidence at the point of collection. Each written finding links directly to the raw evidence from the start. Nothing gets pieced together after the fact. That kind of audit evidence reliability is what gives report conclusions their weight.
Strong evidence, matched precisely to the assertion it must prove, lifts the credibility of everything else in your report. It’s the one improvement that pays off across every section. Nothing else you do to a report matters as much if the underlying proof is weak or hard to trace.
The auditor who masters assertion alignment doesn’t just write better reports. That auditor earns the kind of professional influence that makes decision-makers read the next report before it’s even finished.
Conclusion
When your report language ties every conclusion to specific proof, you’ve already done the hardest work. The next step is simple: match each piece of evidence to the exact assertion it must support. Do that consistently, and your findings stop being filed away and start driving real decisions.
Consider a team auditing a retail location’s inventory controls. A photo of a locked stockroom proves physical security, but it says nothing about count accuracy. Pulling the right evidence for the right claim matters most. That focus is what audit evidence collection methods should be built around from the start.
Audit evidence quality enhancement isn’t a compliance checkbox. It’s the discipline that separates auditors whose reports change behavior from those whose reports collect dust. High-quality audit evidence must be grounded in reliability and tested against sufficiency and appropriateness. Only then does it earn the trust that makes decision-makers act.
Every upgrade to your evidence quality is ultimately an upgrade to your professional influence. Most field audit teams lose credibility because their evidence looks complete but fails assertion alignment under scrutiny. FieldPie captures structured, timestamped field data that ties directly to specific audit assertions, so every finding arrives with traceable proof attached.
FieldPie sells an AI-powered field operations platform. It helps businesses manage scheduling, routing, audits, sales, merchandising, and team tracking from a single mobile-friendly tool.